Advanced tax strategies for startup founders
· By Ellen Smith
Founders pour years of their lives into building a company. They think carefully about hiring, product, fundraising and growth, often working nights and weekends to get every detail right. But when it comes to the taxes they'll owe when all of that hard work finally pays off, many leave the planning until a sale is already on the table and lawyers are trading drafts of the purchase agreement.
By then, a lot of the most valuable options are gone. Some strategies only work if they're set up years before an exit. Others depend on paperwork filed within days of receiving shares. Missing those windows can mean paying far more in tax than necessary, sometimes by a margin large enough to change what a founder can do next, whether that's starting another company, investing in others or simply taking some time off.
The good news is that a little planning early on can make a very big difference. Most of the steps involved aren't especially complicated or expensive when they're taken at the right time. Below are some of the strategies founders most often discuss with their advisors, along with the reasons timing matters so much for each one.
As always, every situation is different. Tax rules change, and the right approach depends on where you live, how your company is structured, how you received your shares and what you hope to do with the proceeds. Think of this as a starting point for a conversation with a qualified tax professional, not as advice for your specific circumstances.
Start with the qualified small business stock exclusion
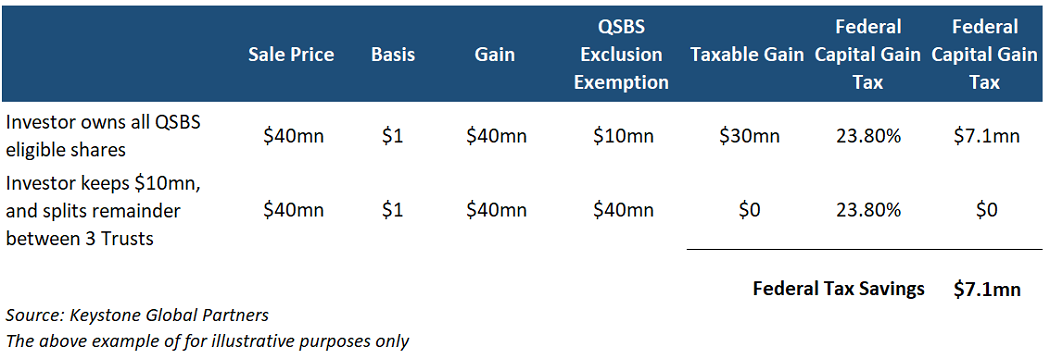
One of the most powerful tools available to startup founders and early employees in the U.S. is the qualified small business stock exclusion, often called QSBS. When it applies, it can allow a shareholder to exclude a significant amount of gain from federal income tax when they sell their shares. In some cases, that can mean paying little or no federal tax on a very large gain.
For founders whose companies grow substantially, the potential savings can be life-changing. That's why it's worth understanding the basics long before a sale is on the horizon, and why many experienced founders bring it up with their advisors as early as the day they incorporate.
Not every company or share qualifies, however. Broadly speaking, the rules look at:
- The type of company: generally a domestic C corporation in a qualifying line of business.
- The size of the company when the shares were issued, measured by its assets.
- How long the shares have been held before they're sold.
Because the holding period starts when the shares are issued, founders who receive their stock early in the company's life are often in the best position to benefit. Shares received later, or through certain kinds of transactions, may be treated differently.
The details can get complicated quickly, especially around company conversions, stock redemptions and how shares were originally acquired. A company that started as an LLC and later converted, for example, may have different starting dates for different shareholders. Keeping clean records from day one, including board approvals, stock certificates and documentation of the company's assets at each issuance, makes it much easier to confirm eligibility later.
It's also worth checking how your state treats the exclusion. Not every state follows the federal rules, so a founder who qualifies at the federal level may still owe state tax on the gain.
Founders should also pay attention to decisions the company itself makes along the way. Buying back shares from investors or employees, raising large amounts of capital or shifting into a different line of business can all affect whether stock continues to qualify. It's worth asking the company's lawyers to flag any transaction that could have an impact before it's approved, rather than discovering the problem during due diligence for a sale.
Early employees who hold stock rather than options may be able to benefit from the same rules, which is one reason some startups encourage early hires to exercise options sooner. That decision comes with its own costs and risks, since exercising means paying for shares that may never be worth anything, so it's best made with professional advice and a clear view of the company's prospects.
File your 83(b) election on time
Many founders receive shares that vest over several years. Vesting protects the company and co-founders if someone leaves early, but it has tax consequences. By default, the tax system may treat each batch of vesting shares as income when it vests, based on what the shares are worth at that moment.
If the company has grown in value by the time shares vest, that can create a large tax bill on stock that the founder can't easily sell. Startup shares are usually illiquid, which means a founder could owe real money on paper gains long before they ever see any cash.
An 83(b) election lets a shareholder choose to be taxed on the value of the shares when they're granted instead of when they vest. For founders, the value at grant is often very low, sometimes a fraction of a cent per share, which can keep the immediate tax cost small or even close to zero.
Just as important, making the election can start the clock on holding periods earlier, which may matter for capital gains treatment and for other strategies down the line. For some founders, that earlier start date ends up being worth far more than the tax saved at grant.
The catch is timing. The election generally has to be filed within a short, strict window after the shares are granted, and late filings usually aren't accepted. It's one of the easiest planning steps to take and one of the most painful to miss. Many founders keep a copy of their filed election and proof of mailing with their most important company records, since it may be needed again years later.
Multiply the benefit by gifting shares
Some tax benefits are capped per taxpayer. For founders with significant holdings, that can mean part of their gain falls outside the benefit and is taxed in the usual way.
One approach advisors sometimes discuss is gifting shares to family members, or to certain types of trusts, well before a sale. In some situations, each recipient may be able to claim their own benefit on the shares they hold, which can significantly increase the total amount of gain that's sheltered.
Gifting early also has estate planning advantages. Shares given away while the company's value is still modest use up less of a founder's lifetime gift allowance than the same shares would after the company has grown. A gift that's worth relatively little today could be worth many times more by the time of an exit.
Any future growth on those shares then happens outside the founder's estate, which can reduce estate taxes later on. For founders who already know they want to support children, siblings or other relatives, it can be one of the most efficient ways to do it.
These strategies involve legal documents, valuations and careful structuring, so they're not do-it-yourself projects. The type of trust used, who serves as trustee and how the gift is documented can all affect whether the strategy works as intended. Done well and done early, though, they can benefit both the founder and the people they care about.
Done too late, they may not work at all. Gifts made right before a sale can attract extra scrutiny, and the value of the shares may already be locked in at a much higher level, eating up more of the founder's gift allowance for the same number of shares.
Give to charity with appreciated stock
Founders who plan to give to charity can often do more good by donating shares instead of cash. Many founders have causes they care deeply about, and an exit can be the first time they're in a position to make a meaningful gift.
When appreciated stock is donated directly to a qualified charity, the donor may be able to avoid paying capital gains tax on that appreciation, while still claiming a charitable deduction. The charity receives the full value of the shares, and because charities generally don't pay tax when they sell, more of the money ends up going to the cause.
Two common ways founders set this up are:
- Donating shares directly to a charity, either before or after an exit, depending on the circumstances.
- Contributing shares to a donor-advised fund, which lets the donor take a deduction now and recommend grants to charities over time.
As with gifting, timing matters. Donating shares before a sale agreement is signed is generally treated differently from donating them after a deal is effectively done. If the sale is already a near certainty, the donor may be treated as if they sold the shares themselves first, which can wipe out much of the benefit.
Plan before the term sheet arrives
The common thread running through every one of these strategies is time. The earlier founders start, the more options they have, and the more value those options can deliver. Many of the most effective steps cost very little to take early and are impossible to take late.
Once a sale is being negotiated, many doors start to close. Valuations rise, deadlines approach and there's simply less room to make thoughtful decisions. Founders in the middle of a deal are also stretched thin, managing employees, investors and buyers all at once, which leaves little energy for personal planning.
Where you live can matter as much as what you own. State income tax rates vary widely, and some states don't tax capital gains at all. Founders who are already considering a move for personal reasons sometimes look at whether timing it before a sale makes sense. States take residency seriously, though, and a move made mostly on paper rarely holds up. Genuinely relocating your life, your home and your day-to-day ties is what counts.
Liquidity events also don't always look like a clean sale of the whole company. Secondary sales, tender offers and partial acquisitions can all trigger tax, sometimes on only part of a founder's holdings. Knowing in advance which shares you'd sell first, and how each would be taxed, can make it easier to say yes to an opportunity when it appears.
A good first step is to put together a small team of advisors, typically a tax professional and an attorney who regularly work with startup founders, and meet with them well before any exit is in sight. A financial planner can also help connect tax decisions to bigger life goals.
Bring your cap table, your stock agreements and a rough idea of your personal goals. Those goals might include supporting family, giving to causes you care about, investing in other startups or simply making sure you keep as much of your hard-earned gain as the rules allow. Revisit the plan every year or two, and again whenever the company raises a major round.
Building a company is hard enough. With a little planning, founders can make sure that when the big moment finally arrives, they're ready for it, and that the rewards of all those years of work go where they intend.
Filed under:Technology
You Might Also Like…
Here’s How To Add Pronouns To Your Instagram Profile In A Few Simple Steps
A new profile field makes it easier to show how you'd like to be addressed. It only takes a minute to set up, and you decide who gets to see it.
· By Ellen Smith
Do we have any control over what the post-pandemic world looks like?
As restrictions lift and routines return, we're all starting to picture a new normal. How much of it is really up to us?
· By Ellen Smith
Ford adds Alexa voice assistant to new cars
“Alexa, what's the traffic like on my commute?” Asking your car for help is about to get a lot more natural.
· By Ellen Smith